PREMIER Credit Card

Screenshots
Details
- Rating
- 16.37K reviews
- Version
- 3.19.5
- Developer
- PREMIER Bankcard
Analysis by Norviv
If you have a PREMIER Bankcard credit card and want a simpler way to keep an eye on it, PREMIER Credit Card is built around one clear job: helping you manage that card from your phone. I found it most useful as a practical account companion rather than a full personal-finance platform. It does not try to organize every bank account, investment, bill, or spending category in one place. Instead, it keeps the focus on the PREMIER card relationship, which makes the experience easier to understand for a first-time user.
The app is free to install, carries an Everyone age rating, and comes from PREMIER Bankcard. It belongs in the finance category and has attracted a 4.6 average from roughly 252 thousand ratings, with more than a million installs. Those figures suggest that it has become a familiar tool for many cardholders, but popularity is not the main reason I would recommend it. The real question is whether you want a direct mobile route to your PREMIER account instead of relying on a browser, paper statements, or occasional phone calls.
What to expect when you open the account app
My first impression is that this is a focused utility. You open it because you need to check something about your PREMIER Bankcard account, not because you want to browse financial education or build a detailed household budget. That narrow purpose is a strength when you already know which card you need to manage. It also sets a useful expectation: the app is most valuable during small, frequent moments when waiting for a computer would be inconvenient.
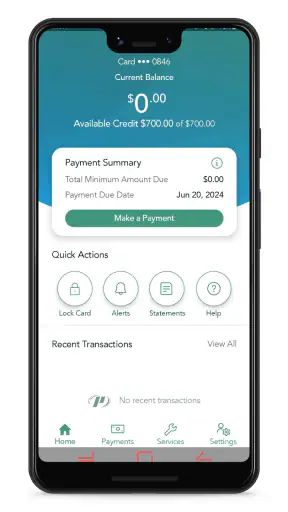
A realistic example is checking your available credit before making a larger purchase. I would rather confirm the account from my phone while standing in a shop than guess from memory or search through an old statement. The same applies when I want to review recent activity after using the card, make sure a payment has been reflected, or confirm an account detail before contacting support. These are ordinary tasks, but quick access can make them less stressful.
The experience should not be confused with a replacement for every financial service. A general banking app may be better if you need checking-account transfers, savings goals, investment tracking, or a combined view of several cards. A budgeting app may be better for detailed categories and long-term spending analysis. PREMIER Credit Card makes more sense when the card itself is the center of the task.
I also appreciate that the app is not presented as a complicated financial dashboard. For someone who is new to mobile account management, a smaller scope can feel reassuring. You are not being asked to learn an entire money-management system before completing a basic action. The trade-off is that users expecting a broad financial hub may find the experience limited.
The right expectations prevent most disappointment
Before installing, I would ask one simple question: do I have a PREMIER Bankcard account that I want to manage digitally? If the answer is yes, the app has a clear reason to be on the phone. If the answer is no, there is little value in downloading it just to explore. This is not a general-purpose wallet or a universal card manager.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
I would also treat it as a companion to responsible account habits, not as a substitute for them. Seeing an account on a screen does not automatically make spending easier to control. The useful routine is to check the account deliberately, understand what has changed, and act before a small issue becomes a larger one. In my experience, the app is strongest when it supports that routine without adding unnecessary steps.
Setting it up without getting stuck
The first setup should begin with the same care I would use for any financial application. I would install it only on my own phone, use a private connection when possible, and keep my card or account information nearby. The app runs on Android devices using version 7.0 or later, so compatibility is worth checking before spending time on installation. It is currently version 3.19.5, which is useful context when comparing what appears on your device with current guidance from PREMIER Bankcard.
After opening the app, I would follow the sign-in or account-access path shown on screen rather than trying random credentials repeatedly. A common first-time mistake is assuming that a card number alone is enough to create or access every digital account. If the app asks for account details or identity information, enter them carefully and stop to check spelling before submitting. Financial apps are less forgiving of small errors than casual social applications.
Another practical tip is to decide in advance where you keep your login information. I would avoid saving it in an exposed note or sharing it through messages. If the phone offers a secure system method for remembering credentials, that is more sensible than reusing a simple password. I would also avoid completing setup while someone is watching the screen, especially if the device is being used in a public place.
The first launch is a good time to confirm that you are looking at the intended PREMIER account. I would read the account identifiers and recent information instead of tapping through automatically. This small pause matters if you manage more than one card or if a household member also uses a PREMIER product. Recognizing the correct account before taking action is one of the easiest ways to prevent an avoidable mistake.
What to do if the first login feels unclear
If the sign-in process does not work on the first attempt, I would not keep guessing. Repeated attempts can create more confusion and make it harder to remember which information was entered. I would check that the app is current, verify the connection, and use the recovery or help route displayed within the account-access flow. If the issue concerns card status or identity verification rather than the phone itself, contacting PREMIER Bankcard through its official support channel is the safer next step.
This is also where the app’s focused design has a limitation. A broad banking application may guide users through several kinds of account recovery in one place, while a card-specific application naturally keeps its attention on PREMIER account access. That is not a flaw for an established cardholder, but it means a completely new user may need to be patient during the transition from physical card management to digital access.
Once setup is complete, I would spend a minute learning the labels and navigation before trying to change anything. That short orientation reduces the chance of confusing a balance view with a payment action or overlooking recent activity. I prefer this approach to tapping every button simply to see what happens, because financial actions deserve a little more caution than ordinary app exploration.
Finding the first meaningful success
For a first-time user, the best first success is not changing a setting. It is opening the account and confirming that the information you need is available in a form you can understand. I would sign in, review the visible account summary, and then look at recent activity. This establishes that the account is connected correctly and gives me a baseline for future checks.
Imagine receiving a notification or remembering a purchase from earlier in the day. I would open the app, locate the account activity, and compare the displayed information with my receipt. If everything looks familiar, I have completed a useful task without waiting for a statement. If something looks unfamiliar, the app has helped me identify an issue early enough to investigate rather than discovering it much later.
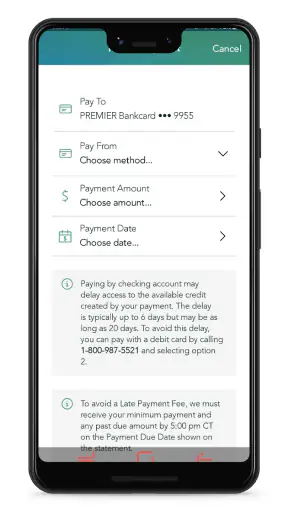
The next action I would practice is checking the information needed before a payment decision. I would review the account carefully, consider the amount I can comfortably pay, and use the available payment route only after confirming the destination and amount. The important insight here is that the app can make a payment workflow more convenient, but convenience should not turn into automatic tapping. I always want a final review before submitting anything related to money.
That review step is especially valuable for people who use their card around several recurring expenses. A quick account check can help distinguish a newly posted purchase from an older transaction or a pending item. It can also prevent the common mistake of assuming that a payment or purchase has already changed every account figure immediately. Account information can update at different points in a transaction’s life, so I would use the displayed status as a guide and keep receipts for anything that needs later confirmation.
A routine that makes the app genuinely useful
I would create a small weekly habit rather than opening the app only when something feels wrong. During that check, I would review recent activity, look at the account position, and note anything that needs follow-up. This takes less effort than reconstructing several weeks of card use after a surprise. It also turns the app into an early-warning tool instead of an emergency tool.
A second useful routine is checking before a planned purchase when the amount matters. I would not rely on a remembered balance because recent activity, pending items, and payments can affect what I expect to see. Confirming the account immediately before spending gives me a more realistic starting point. This is a small but non-obvious advantage of mobile access: the check can happen at the moment a decision is being made, not only at home.
For households, I would agree on who reviews the account and how unusual activity is handled. The app can show the account to the person who signs in, but it does not remove the need for clear communication between card users. If a transaction is unfamiliar, I would record the date, merchant description, and amount before contacting PREMIER Bankcard. Having those details ready makes the conversation more efficient than simply saying that something “looks wrong.”
Common points of confusion during everyday use
The most likely confusion is expecting the app to provide the same kind of complete financial picture as a budgeting service. It is centered on a PREMIER Bankcard account, so I would not expect it to automatically become a household ledger. If your main goal is seeing spending across multiple institutions, a broader finance tool may suit you better. You can still use both: this app for direct card management and a separate tool for wider planning.
Another point of friction is interpreting account activity. A transaction that appears in a list may not mean that every related account figure has settled in the way you expect. I would avoid treating one screen as a guarantee that a purchase, payment, or adjustment is fully completed. When timing matters, I would check the status carefully and keep supporting records until the transaction is clearly resolved.
Users may also wonder whether mobile access makes a browser unnecessary. For quick checks, I found the phone approach more convenient. For a longer review, typing carefully, or handling a situation that requires detailed support, a browser or direct contact may still be more comfortable. The best choice depends on the task. The app is not automatically better simply because it is on a phone.
Notifications and phone habits can create another subtle issue. I would be careful about displaying account-related alerts on a lock screen where other people might see them. I would review the device’s notification settings and choose a level of detail that fits my privacy needs. This is not a reason to avoid the app; it is a reminder that mobile convenience also places financial information closer to everyday surroundings.
When another option is the better choice
I would skip this app if I do not have a PREMIER Bankcard account, or if I am searching for a single dashboard that combines cards from different issuers. I would also choose a dedicated budgeting application when my priority is detailed category analysis, shared household planning, or long-term spending reports. Those tools solve a different problem more directly.
On the other hand, I would prefer PREMIER Credit Card over a general budgeting app when I need the most direct view of my PREMIER account. A third-party tool may be convenient for summaries, but a card-specific app is the place I would start for account-focused checks and actions. Keeping that distinction in mind helps avoid blaming the app for not being designed as something else.
The app is also not ideal for someone who rarely uses a smartphone or who feels uncomfortable entering financial information on a mobile device. In that case, a browser or traditional support route may feel more manageable. I would rather use a method I can operate confidently than adopt an app purely because it is available.
My next-step recommendation for a new cardholder
After the first successful sign-in and account review, I would make the app part of a simple three-part routine: check recent activity, confirm the account position before important purchases, and review payment details before submitting an action. I would not open it compulsively or treat every small change as an emergency. The goal is steady awareness, not constant monitoring.
I would also keep the physical card information and official support details available separately. A mobile app is convenient, but a locked phone, connection problem, or account-access issue can interrupt that convenience. Having a backup way to identify the account and request help is sensible, particularly when a payment deadline or unfamiliar transaction requires attention.
For readers deciding whether to install it, my recommendation is straightforward. If you already use a PREMIER Bankcard and want a dedicated phone-based way to manage it, this free finance app is a sensible starting point. Its broad adoption and strong 4.6 average are encouraging, but its real appeal is the focused workflow: open the account, understand what has happened, and take the next step with fewer delays.
My final view is positive, with a clear boundary. I would recommend it to a PREMIER cardholder who values direct access and wants to replace occasional browser checks with a more immediate routine. I would not recommend it as the only financial app for someone who needs multi-bank budgeting or a complete money overview. Used for the job it was made to handle, PREMIER Credit Card feels practical, approachable, and most useful when it turns a vague account worry into a quick, informed check.
Frequently Asked Questions
01What is the PREMIER Credit Card, and who is it designed for?
The PREMIER Credit Card generally refers to credit card products offered by PREMIER Bankcard, which are primarily designed for people who are building or rebuilding their credit history. Approval, credit limits, fees, interest rates, and available features can vary by applicant and product. Before applying, carefully review the official offer to understand the total cost and whether the card matches your financial situation.
02Can the PREMIER Credit Card help me build my credit score?
A PREMIER Credit Card may help establish or rebuild credit when the account is used responsibly and payments are made on time. Depending on the product and reporting practices, account activity may be reported to major credit bureaus. However, using too much of the available limit, missing payments, or applying for multiple accounts can negatively affect your credit. Check the current terms to confirm reporting details.
03What fees and interest charges should I check before applying?
Applicants should carefully examine the cardholder agreement for the annual fee, monthly maintenance fees, program fees, late-payment charges, returned-payment fees, cash advance costs, foreign transaction fees, and purchase APR. Some fees may reduce the available credit shortly after opening the account. Because pricing can differ between offers, do not rely only on advertisements—review the official disclosure and calculate the likely cost of carrying a balance.
04How do I apply for a PREMIER Credit Card and what information is required?
Applications are normally completed through the official PREMIER Bankcard website or another authorized application channel. You may be asked for identifying information, your Social Security number or equivalent tax identification details, income, housing information, and employment details. Make sure the website or app is legitimate before entering sensitive data, and remember that submitting an application can result in a credit inquiry depending on the specific offer.
05How can I manage my PREMIER Credit Card after approval?
After approval, cardholders can typically manage their account through the official online portal or mobile app, depending on the services available for their account. Common tools include checking the balance, viewing transactions and statements, making payments, monitoring the available credit, and updating account information. Enable notifications where available, pay at least the required amount before the due date, and contact official customer support if you notice suspicious activity.


